You might think of G – I – R – L – S when recalling the accounts that are increased with a credit. You might think of D – E – A – L when recalling the accounts that are increased with a debit. To debit an account means to enter an amount on the left side of the account. To credit an account means to enter an amount on the right side of an account. Each account can be represented visually by splitting the account into left and right sides as shown.
- Since Accounts Payable increases on the credit side, one would expect a normal balance on the credit side.
- It is a fundamental concept in accounting that helps ensure accuracy and consistency in financial reporting.
- By storing these, accountants are able to monitor the movements in cash as well as it’s current balance.
- A company has the flexibility of tailoring its chart of accounts to best meet its needs.
- Each of the five primary account types—Assets, Liabilities, Equity, Revenue, and Expenses—has a specific normal balance, which is the side (debit or credit) that increases that account.
Asset account
In this case, the revenue generated from the sale of the product from the supplier is usually shown as a credit on the accounts payable. The contra accounts appear directly below the real account in the financial statements. The purpose of the Contra accounts is usually to offset the balance from the original account. The account is debited when expenses are incurred and credited when payments are made. The debit side of a liability account represents the amount of money that the company has paid to its creditors.
What is the difference between normal balance and abnormal balance?
This balance forms the basis for reliable financial statements. Owner’s Equity, representing the owners’ residual claim on the assets of the business after liabilities are deducted, also has a normal credit balance. Increases in owner’s equity, such as owner investments or net income, are recorded as credits. Decreases, like owner withdrawals or net losses, are recorded as debits. This aligns with the accounting equation, where liabilities and equity are on the opposite side of assets.
Normal Balance for an Account
Meanwhile, liabilities, equity, and revenue represent money coming in or claims on the company. Cash on hand should never have a net credit balance, https://shop.techswitchcf.com/become-a-certified-proadvisor-quickbooks-intuit-7/ since one cannot credit (pay from) cash what has not been debited (paid in). It would properly be reported as an asset, and possibly written off to a zero balance if the overpayment is not recoverable. Equity, which signifies the owner’s stake in the business, also carries a normal credit balance.
In the double-entry system, Equipment (an asset) is debited for $10,000, reflecting that it is an asset and thus has a Normal balance of debit. At the same time, Accounts Payable (a liability) is credited for $10,000, respecting that liabilities have a Normal balance of credit. By adding this journal entry, the accounting equation remains in balance.
What is a Normal Balance in Accounting?
On the other hand, the balance of an account refers to the actual amount of money or value in the account at a specific point in time. The revenues a company earns from selling the products are usually credit in accounts payables on the normal balance. This usually happens for the retailers, who sell the things they receive on credit to the consumer. The credit is the usual version of the normal balance for the accounts payable. Every company has a usual paying period for the accounts receivables of about one to three months.
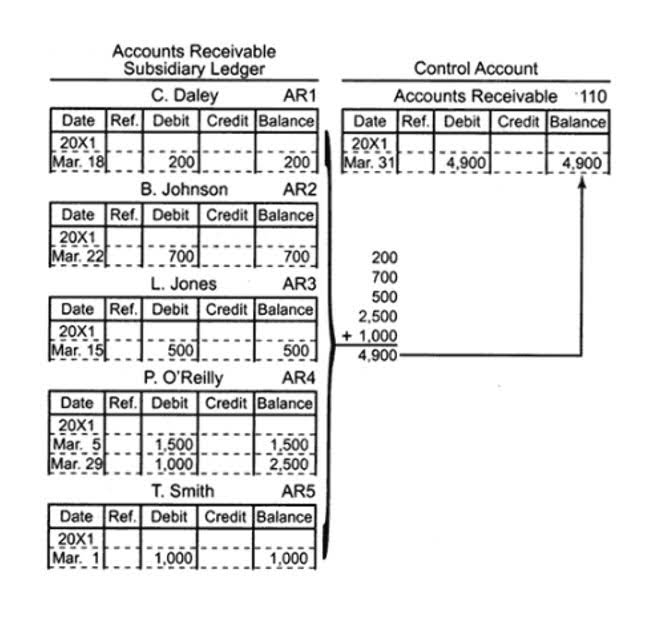
Example of the Normal Balance for an Account
In conclusion, you’ve seen how crucial understanding the normal balance of accounts is. It’s about knowing how to identify increases and decreases, applying this knowledge practically, and keeping accurate records. Understanding how increases and decreases in your financial records impact your business’s overall financial health is crucial.
- Accounts such as Accounts Payable, Notes Payable, and Unearned Revenue fall into this category.
- The normal balance is the expected balance each account type maintains, which is the side that increases.
- Asset accounts normally have debit balances, while liabilities and capital normally have credit balances.
- Revenues and gains are recorded in accounts such as Sales, Service Revenues, Interest Revenues (or Interest Income), and Gain on Sale of Assets.
- Each type of account within the accounting system has an expected normal balance, which is either a debit or a credit.
- One common area that often raises questions is what is the normal balance of sales returns and allowances?
Learning about financial entries is key for keeping accurate records. contra asset account Real-life examples show us how transactions can affect accounts. They highlight the importance of understanding journal entries in everyday business. For reference, the chart below sets out the type, side of the accounting equation (AE), and the normal balance of some typical accounts found within a small business bookkeeping system. Predictive analytics is the compass that guides financial voyagers through the sea of data towards tomorrow’s budgeting shores.
How does the accounting equation relate to normal balances?
Others use the word to signify a net amount, such as income from operations (revenues minus expenses in the company’s main operating activities). Still others use it when referring to nonoperating revenues, such as interest income. The book value of a company equal to the recorded amounts of assets minus the recorded amounts of liabilities. Accounts Receivable is an asset account and is increased with normal balance a debit; Service Revenues is increased with a credit. Now, let’s move on to discussing the concept of normalizing entries in accounting.
By adhering to the expected normal balances, accountants maintain the integrity and usefulness of the financial statements. Having a clear understanding of the normal balance of different accounts is essential for maintaining accuracy and consistency in accounting practices. It allows for proper classification of transactions and ensures that financial statements reflect the true financial standing of the entity.
Lascia un commento